A company received funding for the implementation of a project. Following a project control, the funding institution concluded that some or all of the funding had to be repaid. The decision requiring repayment became final, but the company, as the funding recipient, did not pay the amount due. Enforcement proceedings were then initiated, but the amount could not be recovered from the company’s assets.
This sequence of events raises the question of whether a management board member may become personally liable for repayment of the funding.
A decision requiring the company to repay funding does not automatically make a management board member liable to pay the same amount from their personal assets. Establishing such liability requires separate proceedings and an assessment of whether the statutory conditions governing third-party liability have been met.
Where funding originates from European funds, this mechanism results from the combined application of the Public Finance Act and the relevant provisions of the Tax Ordinance Act. This cross-reference means that, in certain circumstances, a management board member may be held liable for a company’s public-law obligation.
Who is required to repay the funding?
The obligation to repay the funding rests with the funding recipient, i.e. the company. This distinction is fundamental to the further course of the case. The fact that a particular person represented the company when the grant agreement was signed, submitted payment applications, or corresponded with NCBR or PARP does not in itself make that person a debtor in respect of the repayment obligation.
Why can liability for repayment extend to a management board member?
An obligation to repay funds allocated to programmes financed with European funds is a public-law obligation. This is also important where the funding recipient is a commercial company.
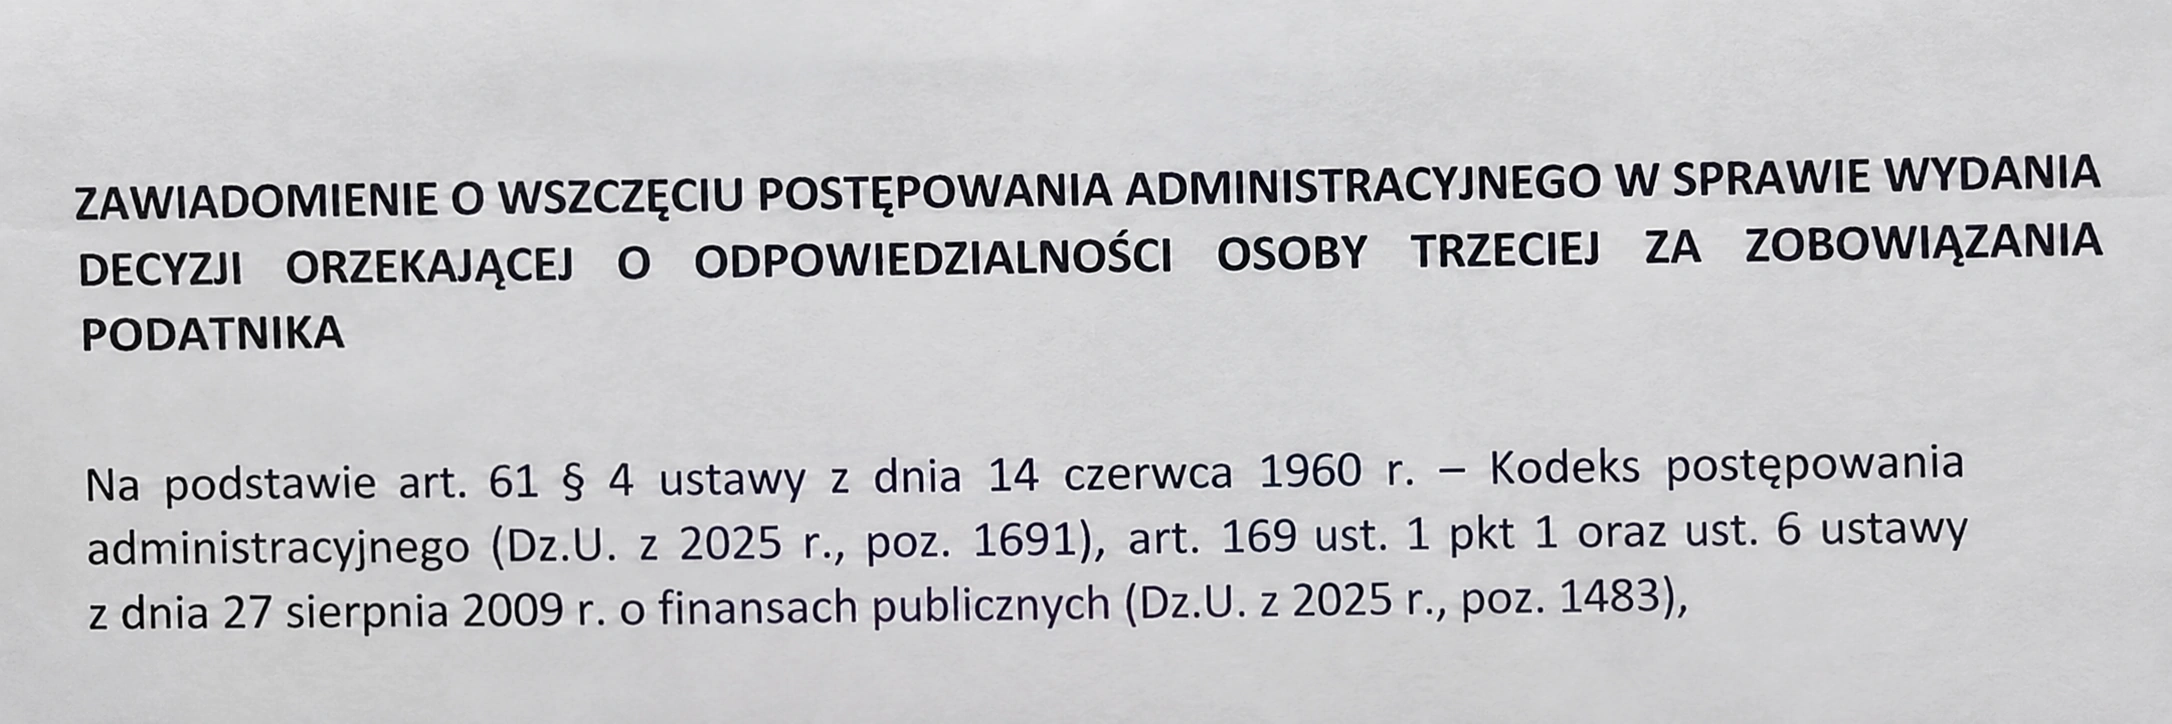
The Public Finance Act provides for the corresponding application of the provisions of the Tax Ordinance Act concerning third-party liability. These provisions include rules under which, if specific conditions are met, liability for a company’s obligation may be attributed to members of its management board.
This does not mean that the repayment obligation becomes a tax liability or that a management board member becomes liable for it as soon as a decision concerning the company is issued. The provisions of the Tax Ordinance Act provide a mechanism for establishing third-party liability, which must be applied taking into account the specific rules of the Public Finance Act. In practice, the starting point remains the funding recipient’s obligation to repay the funds. Only at a later stage may a separate issue arise as to whether a management board member can be held liable for an obligation that the company has failed to discharge.
Is a decision requiring the repayment of funding sufficient to establish a management board member’s liability?
No. Two separate stages must be distinguished:
- the decision determines the amount to be repaid, the date from which interest accrues, and the manner in which the funds are to be repaid. It is addressed to the funding recipient, i.e. the company;
- if the company fails to pay the amount due, separate proceedings may be initiated to determine whether a particular third party is liable for the company’s existing obligation. Those proceedings are subject to their own statutory conditions and conclude with a separate decision.
The distinction between these two sets of proceedings is also confirmed by case law. In its order of 29 April 2026, the Supreme Administrative Court indicated that proceedings concerning the liability of a management board member examine whether the statutory conditions for holding that person liable for the company’s obligation have been met. The amount subject to repayment, however, had already been determined earlier in separate proceedings conducted against the funding recipient.
The separation of the two sets of proceedings also has procedural significance. A management board member’s liability is determined by the authority in a separate decision, and the applicable provisions specify the conditions that must be met before such proceedings can result in liability being imposed on the management board member.
This is illustrated by a judgment of the Voivodeship Administrative Court in Bydgoszcz of 14 April 2026. The Court challenged the decision concerning the liability of a management board member because it had not been properly established whether the earlier decision imposing the repayment obligation on the company had been effectively served on it. For a management board member, this means that proceedings concerning their liability may also require an assessment of whether earlier procedural steps taken against the company itself were carried out correctly.
When can a management board member become liable for repayment of funding?
The basic mechanism governing the liability of management board members is set out in Article 116 of the Tax Ordinance Act, which applies accordingly to amounts due in connection with the repayment of funds. These rules may apply to members of the management boards of companies with share capital, including former management board members. However, the mere fact that a person held a position on the management board is not sufficient to establish liability.
The authority must first establish that the company has an outstanding obligation, that the person concerned falls within the category of third parties to whom liability may be attributed, and that enforcement against the company’s assets has proved ineffective. Only once those conditions have been met can the liability of a particular management board member be assessed.
A judgment of the Voivodeship Administrative Court in Gorzów Wielkopolski provides a good illustration of how such a case typically proceeds. First, a decision was issued requiring the company to repay the funds. The amount due was then referred for administrative enforcement. Enforcement did not result in recovery from the company’s assets and the enforcement proceedings were discontinued. Only afterwards were separate proceedings initiated against the president of the management board, resulting in a decision concerning his joint and several liability with the company.
This sequence illustrates the practical purpose of third-party liability. The authority does not begin by pursuing the assets of a management board member. The company’s obligation arises first, and steps are taken to enforce it against the funding recipient.
One qualification is necessary, however. Article 108 of the Tax Ordinance Act does not in itself require proceedings against a third party to be preceded by the formal discontinuance of enforcement proceedings against the company. Ineffective enforcement is, however, a necessary condition for holding a management board member liable under Article 116 of the Tax Ordinance Act. This shows that the typical sequence runs from enforcement against the company to a decision concerning a management board member, although the conditions for initiating proceedings should not be confused with the conditions for issuing a decision establishing liability.
Which management board member may be liable for repayment of funding?
In a company implementing a multi-year project, the composition of the management board may change between the receipt of funding, project implementation, a project control, the issuance of a repayment decision, and the initiation of proceedings concerning a management board member’s liability. It is therefore not enough simply to determine who is serving on the management board when the repayment decision is issued. That does not yet answer the question of who may be held liable.
The Public Finance Act contains a specific rule in this respect. Under Article 66b(2) of that Act, the third parties potentially liable for obligations to repay funds are identified by reference to the situation existing on the date on which the breach giving rise to the repayment obligation occurred.
Accordingly, where funding is repayable under Article 207 of the Public Finance Act, it is first necessary to determine when the breach on which the authority bases the repayment obligation occurred. Only then can it be assessed who was serving on the management board at that time and whether the remaining conditions for liability may be met in relation to that person.
This is particularly important in practice for persons who joined the management board only after the event giving rise to the repayment obligation, or who left the board before a project control or repayment proceedings were initiated. The date of the repayment decision does not necessarily correspond to the period relevant for identifying the persons who may potentially be held liable.
Only at the next stage is Article 116 of the Tax Ordinance Act applied accordingly. It sets out the remaining conditions for the liability of management board members, including ineffective enforcement and the circumstances in which a person may be released from liability.
This is also important because Article 116 § 2 of the Tax Ordinance Act, in relation to tax liabilities, refers to a payment deadline falling during the period in which the person served on the management board. In cases involving repayment of European funds, that rule cannot simply be transferred mechanically. The Public Finance Act contains a specific provision identifying the point in time by reference to which the third parties potentially liable for the repayment obligation are determined.
Can a former management board member be liable for repayment of funding?
Yes. Resignation, dismissal, or expiry of a mandate before the proceedings are initiated does not automatically place a former management board member outside the scope of potential liability.
The provisions of the Tax Ordinance Act also apply to former management board members. In each case, however, it is necessary to determine the period relevant to the liability of the particular person and compare it with the date of the breach giving rise to the repayment obligation and the period during which that person actually served on the management board.
As a result, in a case involving a former management board member, the dates of appointment, resignation or dismissal, the company’s corporate records, and the chronology of events in the project itself become particularly important. The fact that a person no longer held office when proceedings were initiated against them does not in itself determine the outcome of the case.
How can a management board member avoid liability?
The initiation of proceedings against a management board member does not in itself mean that a decision imposing liability for the company’s unpaid obligation will be issued. The authority must establish the conditions that allow liability for the company’s obligation to be attributed to that particular person. At the same time, the management board member may rely on circumstances that exclude such liability.
The first group of such circumstances concerns the company’s insolvency. Liability may be excluded where a bankruptcy petition was filed at the appropriate time, or where restructuring proceedings were opened at that time, or an arrangement was approved in proceedings for approval of an arrangement.
Assessing the “appropriate time” requires reference to the Bankruptcy Law. Bankruptcy is linked to the debtor’s insolvency, and Article 21 of the Bankruptcy Law generally provides for a 30-day period for filing a bankruptcy petition from the date on which the grounds for declaring bankruptcy arise.
A second possibility is to demonstrate that the failure to file a bankruptcy petition occurred through no fault of the management board member. It should be emphasised that this is not a matter of the person’s own belief that the company would be able to deal with its debts. In a judgment of 21 January 2026, the Supreme Administrative Court confirmed the objective nature of this condition and assessed the conduct of the management board member by reference to the degree of care required in managing the company’s affairs.
A third possibility follows from Article 116 § 1(2) of the Tax Ordinance Act. A management board member may identify company assets from which enforcement would allow a substantial part of the outstanding amount to be recovered. What matters, therefore, is the identification of specific, existing assets that can actually be subject to enforcement, rather than a general assertion that the company still has assets.
The appropriate defence therefore depends on the specific course of the case. Financial records may help establish when the company became insolvent, documentation from restructuring or bankruptcy proceedings may show when particular steps were taken, and corporate records may determine the period during which the person actually served on the management board. Where a management board member identifies company assets, what matters is whether effective enforcement against those assets is realistically possible.
In practice, before preparing a position in the case, it is therefore necessary to reconstruct the company’s situation during the relevant period rather than limiting the analysis to documents relating solely to the publicly funded project.
How do proceedings against a management board member work?
Proceedings concerning third-party liability constitute separate administrative proceedings conducted against a particular management board member. Their purpose is to determine whether the statutory conditions are met for attributing the company’s existing obligation to that person.
The management board member is a party to those proceedings and may submit evidence relating to the conditions governing their own liability. The earlier proceedings conducted against the company must, however, also be taken into account. In particular, the status of the repayment decision, whether it was properly served, the course of enforcement against the funding recipient, and the basis on which that enforcement was found to be ineffective may all be relevant.
Proceedings against a management board member therefore do not start from a blank slate. They are based on an obligation that previously arose on the part of the company, while at the same time having their own subject matter and their own statutory conditions, which the authority must establish in relation to the particular person.
When does the obligation arising from a decision on a management board member’s liability become time-barred?
Article 66b of the Public Finance Act contains specific rules concerning third-party liability for obligations arising from the repayment of European funds. Paragraph 3 of Article 66b governs the limitation period for an obligation arising from a decision on third-party liability. That obligation becomes time-barred after five years, counted from the date on which the decision became final, or from the date referred to in Article 66a(1)(1) or (2), depending on which of those dates is later.
A separate time limit applies to the issuance of the decision establishing third-party liability itself. Under Article 66b(1) of the Public Finance Act, such a decision may not be issued after five years from the end of the calendar year in which the repayment decision became final.
When assessing limitation periods, two distinct issues must therefore be distinguished. The first concerns the period within which the authority may issue a decision on a management board member’s liability. The second concerns the point at which the obligation arising from such a decision itself becomes time-barred. These are separate time limits and should not be conflated.
In practice, the mere fact that five years have passed since the decision requiring the company to repay the funds is not sufficient to assess the position of a management board member. The relevant dates must be identified and it must be determined which of the limitation periods provided for in the Public Finance Act applies in the particular case.
Management board member’s liability for repayment of funding under Article 299 of the Commercial Companies Code
The liability described above is public-law third-party liability. Its legal basis is the Public Finance Act together with the relevant provisions of the Tax Ordinance Act, and it is established by an administrative authority in an administrative decision.
Article 299 of the Commercial Companies Code provides for a separate mechanism of liability of members of the management board of a limited liability company towards the company’s creditors. Although both regimes attach importance to ineffective enforcement against the company, this similarity does not justify treating them as equivalent.
In a case concerning repayment of European funds, the starting point remains the rules governing public-law non-tax budgetary receivables and third-party liability. It is not an action for payment brought against management board members under Article 299 of the Commercial Companies Code.
FAQ
Is a management board member automatically liable when a company is ordered to repay funding?
No. The repayment decision is addressed to the funding recipient. A management board member’s liability as a third party requires separate proceedings, an assessment of the statutory conditions arising, among other things, from Article 116 of the Tax Ordinance Act, and the issuance of a separate decision.
Can NCBR or PARP demand repayment directly from a management board member?
A decision establishing a management board member’s liability for the company’s public-law obligation may be issued if the conditions for third-party liability are met. This is not, however, a direct consequence of the repayment decision issued against the company.
Can a former management board member be liable for repayment of funding?
Yes. Article 116 of the Tax Ordinance Act also applies to former management board members. The fact that a person ceased to hold office before proceedings were initiated against them does not exclude liability if the obligation falls within the period covered by the rules governing that person’s liability.
Does a management board member’s liability require ineffective enforcement against the company?
Yes. For liability under Article 116 of the Tax Ordinance Act, ineffective enforcement against all or part of the company’s assets is one of the conditions that must be established before liability can be attributed to a management board member.
How can a management board member avoid liability?
Article 116 of the Tax Ordinance Act allows a management board member to demonstrate, among other things, that appropriate bankruptcy or restructuring measures were taken in due time, that the failure to file a bankruptcy petition was not attributable to that person, or that company assets were identified from which a substantial part of the outstanding amount could be recovered. The appropriate defence depends on the company’s financial history and the period during which the person served on the management board.